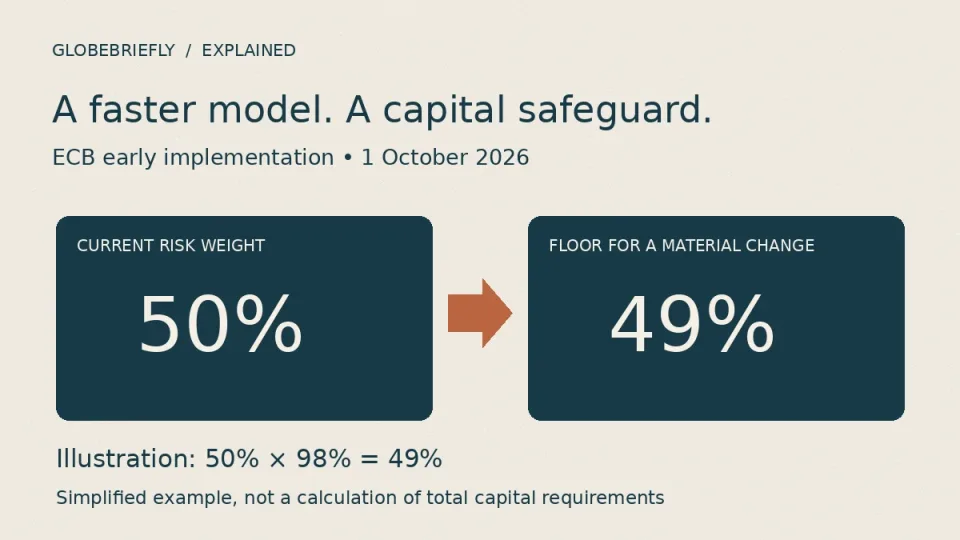
1 October 2026 is the ECB’s published start date for a faster route to implementing material changes and extensions to banks’ credit-risk models. Its July update calls this the “early implementation approach”. The useful question is how a bank can put an updated model to work while limits on its capital benefit remain in place. ECB reform update, July 2026
Why the model matters
Credit-risk models estimate such things as the likelihood of a borrower defaulting and the loss if that happens. These estimates help determine risk-weighted assets, which underpin risk-based capital requirements. A lower modelled risk can therefore affect how much capital a bank needs against its assets. ECB explanation of internal models
What changes in the approval process
Banks seeking this route must submit a complete application. Their internal control function must credibly confirm both regulatory compliance and readiness to implement the revision. The ECB can still require the standard process, including an on-site investigation before implementation, for sensitive cases. ECB announcement and safeguards
The safeguard is tied to existing risk weights:
- Material model changes: a floor of 98% of current risk weights
- Material model extensions: a floor equal to current risk weights
The ECB says lifting the floor requires a targeted on-site assessment. For a simplified illustration, a current risk weight of 50% gives a 49% floor for a material change: 50% multiplied by 98%. That is a 2% relative reduction, not a two-percentage-point reduction. It is not a calculation of a bank’s total capital requirement. ECB announcement and safeguards
Permission still matters
The route accelerates permission rather than eliminating it. Non-material changes and extensions remain subject to notification; initial use of an internal model still requires approval. ECB announcement and safeguards
How to read the example
A floor is a lower bound, not a target or a forecast. The simplified 49% figure above says nothing about the rate a household will pay on a loan. It also does not mean a bank can lower its total capital requirement by 2%. Those are different quantities.
For the broader economic outlook that sits alongside bank supervision, see our guide to the October IMF forecast releases.
Illustration: original GlobeBriefly diagram, made without generative AI. This article explains the announced supervisory process; it does not report a particular bank receiving approval.
KEEP THE CONVERSATION GOING
A good story is worth sharing.
Send this story to someone who values the bigger picture.
See more from GlobeBriefly on Google
Choose us as a preferred source in your Google preferences.