Audio
Listen to the article
- Mexico faces its 2027 budget deadline no later than September 8th with borrowing costs at 9.3% in pesos and 6.4% in dollars.
- The deficit hit 5.7% of GDP in 2024, debt has risen to 63%, and Pemex has absorbed $130bn since 2018, squeezing investment.
- Rating agencies have Mexico just above speculative grade; investors want proof of fiscal repair, not just promises.
Mexico City
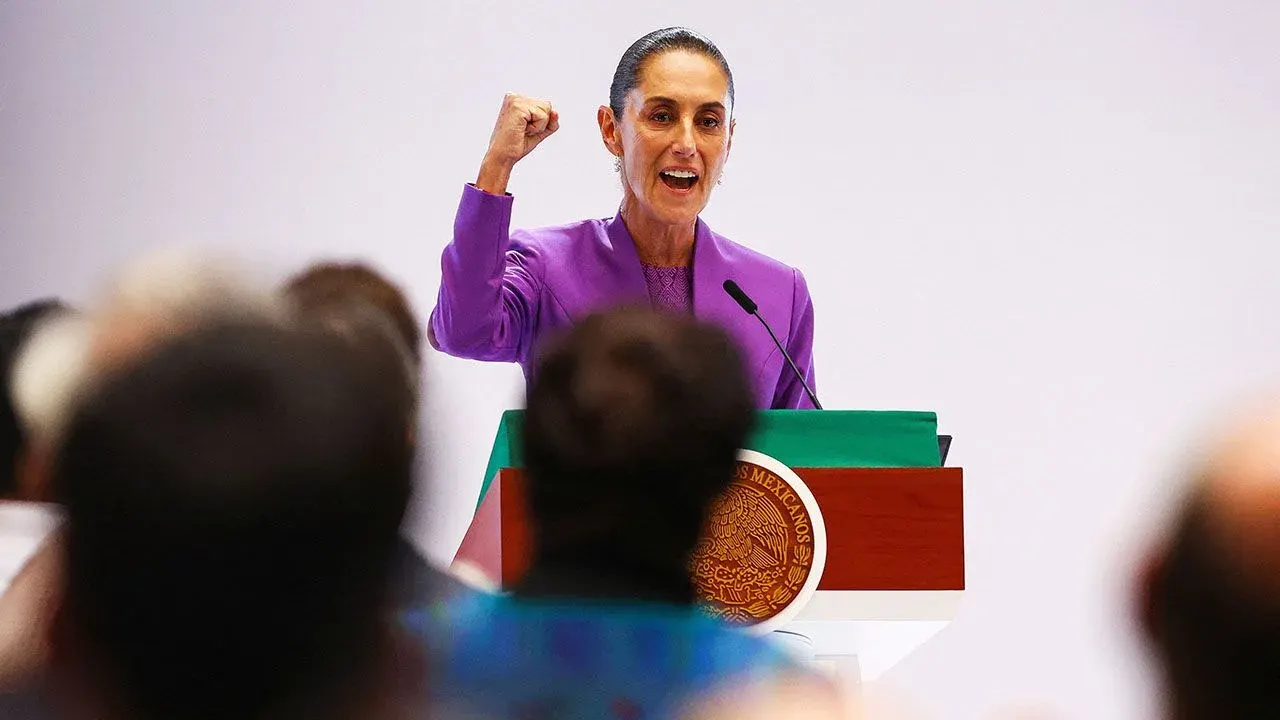
Mexico will table its 2027 budget no later than September 8th, a test of credibility for President Claudia Sheinbaum as bond yields climb and rating agencies circle. Ten-year borrowing costs have risen to 9.3% in pesos and 6.4% in dollars — a premium that now exceeds yields on several sub-investment-grade issuers — while Moody’s, S&P Global and Fitch all place Mexico only just inside investment grade.
10-year peso yield
10-year dollar yield
Two-year trough, last October
Why Mexico’s borrowing costs are rising now
Investor scepticism is centred on the budget. Moody’s cut Mexican sovereign debt in May to just one step above speculative grade. S&P Global has cautioned that it might act next. Fitch already assesses Mexican securities as only marginally investment grade.
That caution is visible in yields. Borrowing in dollars on ten-year paper costs 6.4%, above levels paid by several sub-investment-grade issuers such as Guatemala. In pesos, ten-year funding costs 9.3% for the state, higher than the two-year trough of 8.5% recorded last October.
Budget credibility is key.
Renzo Merino · Moody’s
A deficit near 5% of GDP and debt at 63%
Such credibility had been earned by Mexico across recent decades. Yet in 2024, as Ms Sheinbaum succeeded her mentor and left-wing predecessor, Andrés Manuel López Obrador, the budget shortfall hit 5.7% of GDP, its widest in nearly 40 years. Since then it has stayed near 5%.
Ms Sheinbaum pledges a reduction to 4.1% next year, though that would still be elevated. With expansion close to 1%, state debt has climbed from 52% of GDP in 2019 to 63%. Pensions, welfare payments and interest absorb three-quarters of spending.
Budget shortfall in 2024 — the widest in nearly 40 years — with the deficit still near 5% and a pledge to cut it to 4.1% next year.
Pemex and the squeeze on public investment
Pemex, the national oil company, consumes much of the remainder. The state has channelled $130bn to it since 2018 (excluding off-budget assistance). México Evalúa, a think-tank, estimates that between January and June, for every ten pesos Pemex paid into the treasury, nearly eight returned to the firm.
Consequently, capital spending by the state is meagre, even though faster growth depends on it. Private capital spending is also feeble: it shrank for 19 straight months through the end of March.
Growth, nearshoring and rule-of-law doubts
Expectations that trade tensions would push multinationals to nearshore supply chains near American buyers have largely disappointed. Sentiment has suffered from doubt about the United States-Mexico-Canada Agreement (USMCA), which America’s president is taking apart. At home, changes including the popular election of judges have raised concerns over Mexico’s rule of law.
What Sheinbaum has promised — and what she rules out
Ms Sheinbaum understands these pressures. She has prepared reasonable economic programmes and adopted a friendlier tone toward business than Mr López Obrador. Her aim is for Pemex to cover its own finances by 2027. She has sought extra income by extracting more tax from large corporations and imposing new charges on sugar.
Still, her leftist instincts are increasingly visible. She brushed aside the May Moody’s downgrade as a relic of “the neoliberal era”. She appears reluctant to consider reducing welfare transfers (especially ahead of the 2027 midterm vote). Selling off Pemex is out of the question.
Will Mexico keep its investment-grade rating?
Mexico is likely to avoid the humiliation of speculative-grade status. It remains a big, diverse economy with, at least for now, straightforward entry to the world’s largest market. It would require another shock — a full breakdown of the USMCA, for instance — to trigger that demotion. On August 31st the central bank lifted its growth projection for this year to 1.5%.
Yet to bring Mexican yields down, bond markets need stronger persuasion, especially as soaring debt strains central banks.
Investment grade vs speculative grade — ratings just one step above speculative, or “marginally investment grade,” signal higher borrowing costs and closer scrutiny from bond investors.
For more expert analysis of the biggest stories in economics, finance and markets, sign up to Money Talks, our weekly subscriber-only newsletter.
Sources
Moody’s, S&P Global and Fitch ratings assessments; Mexican 10-year yields (pesos and dollars); budget and debt figures; Pemex transfers; México Evalúa estimate; central bank growth projection. Reporting via Reuters image.
Further reading on GlobeBriefly: global markets and economic data; European bond markets; soaring debt and central banks.
KEEP THE CONVERSATION GOING
A good story is worth sharing.
Send this story to someone who values the bigger picture.
See more from GlobeBriefly on Google
Choose us as a preferred source in your Google preferences.