Audio
Listen to the article
- America’s federal debt has passed $40trn, but its unified federal backing and reserve-currency status cushion the risk.
- The EU owes €15.7trn ($18.2trn) at 83% of GDP — but 27 separate borrowers make it as resilient as its weakest member.
- France, with debt at 118% of GDP, 4.2% 10-year yields and a 2027 election ahead, is now the euro zone’s central fiscal risk.
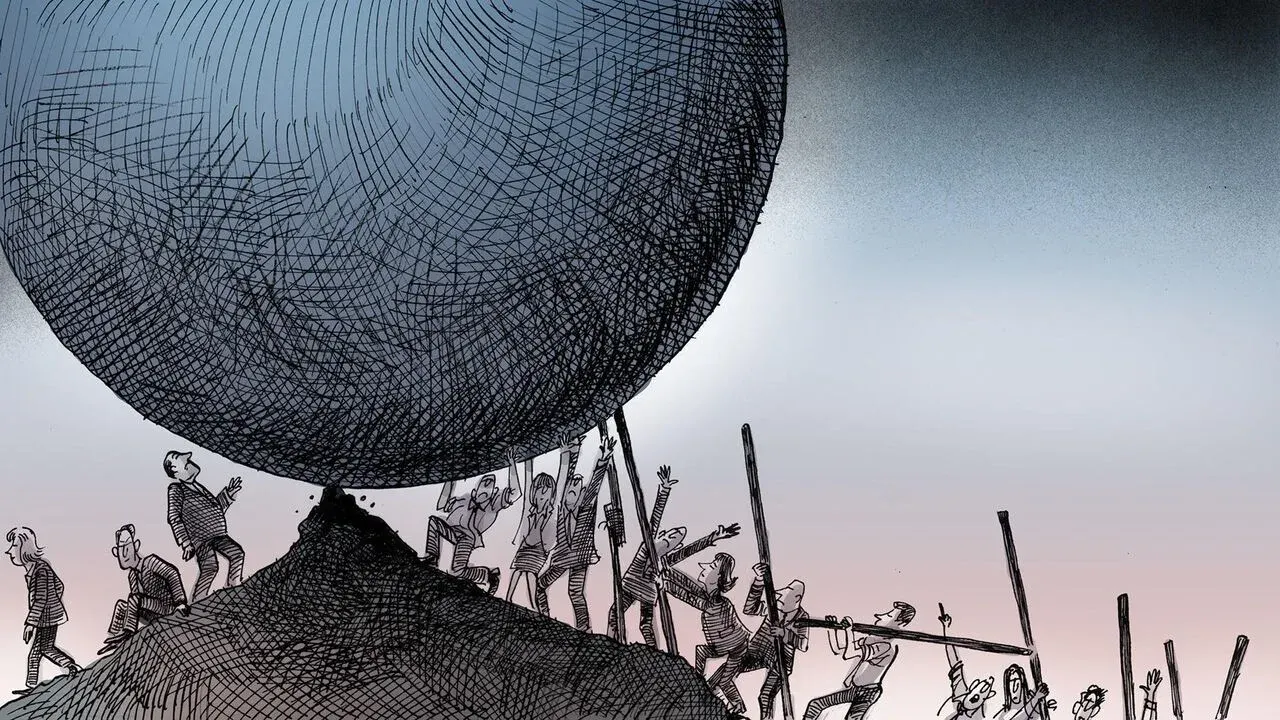
Living in Europe means enjoying refined food, cities built for walking, and endless reminders that its economy trails America’s. So when United States federal debt crossed $40trn in recent weeks and prompted doubts about how much longer bond investors will bankroll chronic deficits, some European circles felt a measure of Schadenfreude. Europe, well versed in runaway debt turmoil, could imagine reversing roles and lecturing Washington on sound stewardship.
At first sight the figures favour the old continent. The combined liabilities of European Union governments total only €15.7trn ($18.2trn), in an economy only modestly smaller than America’s — Europeans earn less but number more. Twenty years ago both had debt-to-GDP ratios near 65%. America’s has since ballooned beyond 120%, and the IMF expects it to exceed 140% by 2031. Europe stands at “just” 83%, with its trajectory roughly stable, still within broadly cautious bounds.
US federal debt
EU debt-to-GDP
US debt-to-GDP, now → IMF 2031
Yet Europeans inclined to preach to Americans — might Washington want a Draghi report of its own? — ought to pause. While America carries the larger debt, Europe carries the more serious debt problem. America benefits from the global reserve currency and an expanding economy. Europe’s handicap boils down to a single word: France.
Why Europe’s smaller debt is more dangerous
Matching European against American borrowing is more complex than top-line totals imply. America certainly owes excessively, but Europe owes in all the most awkward spots. In servicing interest on trillions of federal securities, America is mightier than the aggregation of its components: the whole federation guarantees each dollar borrowed.
In Europe, conversely, most loans are taken on by 27 member states, each obliged to honour its own obligations if the union is to hold together. That leaves the EU — or at least the euro zone forming its centre — as resilient as its frailest member, as Greece demonstrated when it flirted with default.
Many EU states carry controllable loads, above all Germany and its northern neighbours. Others, such as Greece and Spain, hold elevated debt yet generate sufficient growth to calm bond vigilantes. France is distinctive in possessing neither budgetary room — its liabilities equal 118% of GDP — nor momentum — a disappointing 0% in the latest quarter.
France at the centre of the euro zone’s fragility
French yields at 18-year highs
Consequently, yields on French ten-year bonds have now touched 4.2%, their peak in 18 years — even above Italy, the continent’s customary troubled borrower. Partly this reflects a worldwide pattern: states everywhere face dearer interest as investors worry about inflation and geopolitics. But the gap between French and German bonds, the premium Paris must pay creditors to persuade them to accept its riskier paper, now approaches one percentage point.
Dispersion of rates across EU states remains far below the strains witnessed during the euro-zone crisis of the 2010s. That owes much to the European Central Bank, which has since indicated it could intervene were any euro-zone government’s financing costs to climb excessively. Yet the central bank’s support is supposed to depend on the distressed government committing to credible reforms and cleaning up its fiscal disorder.
Elections in 2027 raise the stakes
Politics often obstructs such sensible policy, and Europe faces an abundance of politics ahead. In 2027, national votes are scheduled in France, Greece, Italy and Spain, four heavily indebted nations. Budgetary restraint will likely erode as electors are plied with sweeteners.
France once more stands apart. The polling leader is Marine Le Pen, a populist who previously advocated quitting the euro. Lately, her party’s leader hinted the ECB might be nudged to assist somehow. Her rival on the populist left, Jean-Luc Mélenchon, has declared he wishes to “set fire” to part of France’s government bonds. Even among sensible centrists, no one proposes restoring deficits to 3%, as EU treaties require, anytime soon.
To imply France is the next Greece is exaggerated alarmism — for the moment, at least. Still, French extravagance is already transforming Europe’s fiscal politics.
Why joint EU borrowing is now on hold
America can sustain hefty shortfalls partly because its enormous supply of treasury bills is priced in the world’s reserve currency, making them a handy refuge for jittery investors during turbulent periods. Europe longs to seize a share of this “exorbitant privilege.”
One attempt involved having the EU sell its own federal bonds, collectively guaranteed by all 27 members. The bloc began large-scale issuance in 2021 to fund its pandemic recovery plan. Many expected to sell additional joint debt later to pay for defence outlays, echoing appeals by Emmanuel Macron, France’s president, for greater European “strategic autonomy.”
Yet persistent French fiscal slippage has likely killed prospects for more collective borrowing. The wider the differential between French and German bond yields, the larger the hidden transfer running from Berlin to Paris — and broadly from the cash-rich to the cash-strapped throughout the EU — whenever common bonds are sold. Germany, never enthusiastic about broadening the scheme initially, now holds a powerful objection: who would willingly share a joint account with a profligate whose market creditworthiness is questioned?
French fiscal laxity long imposed a price on the French. Now fellow Europeans are footing the bill as well.
This piece ran in the Europe section of the print edition of September 5th 2026 with the heading “Union dues.”
EU combined liabilities €15.7trn ($18.2trn); EU debt-to-GDP 83%; US debt-to-GDP beyond 120%, IMF forecast above 140% by 2031; both near 65% 20 years ago. French debt 118% of GDP; French 10-year yield 4.2%. Deficit reference 3% under EU treaties. Sources: IMF; national accounts; market pricing.
From the September 5th 2026 edition
Explore more tales from this section and beyond in the table of contents.
KEEP THE CONVERSATION GOING
A good story is worth sharing.
Send this story to someone who values the bigger picture.
See more from GlobeBriefly on Google
Choose us as a preferred source in your Google preferences.