Audio
Listen to the article
- UPI marked its tenth anniversary on August 25th, handling 25bn transfers worth nearly 30trn rupees in August alone, up from 73m transfers worth 227bn rupees in its first year.
- Ubiquity was built on simplicity, cheap data after Jio’s 2016 debut, the November 2016 demonetisation of 500- and 1,000-rupee notes, and zero fees for merchants since 2020.
- Parliament has now re-allowed commercial fees — expected only for large firms above a floor — but the non-profit NPCI system and banks still rely on small subsidies that leave little for upkeep, fraud prevention or innovation.
India
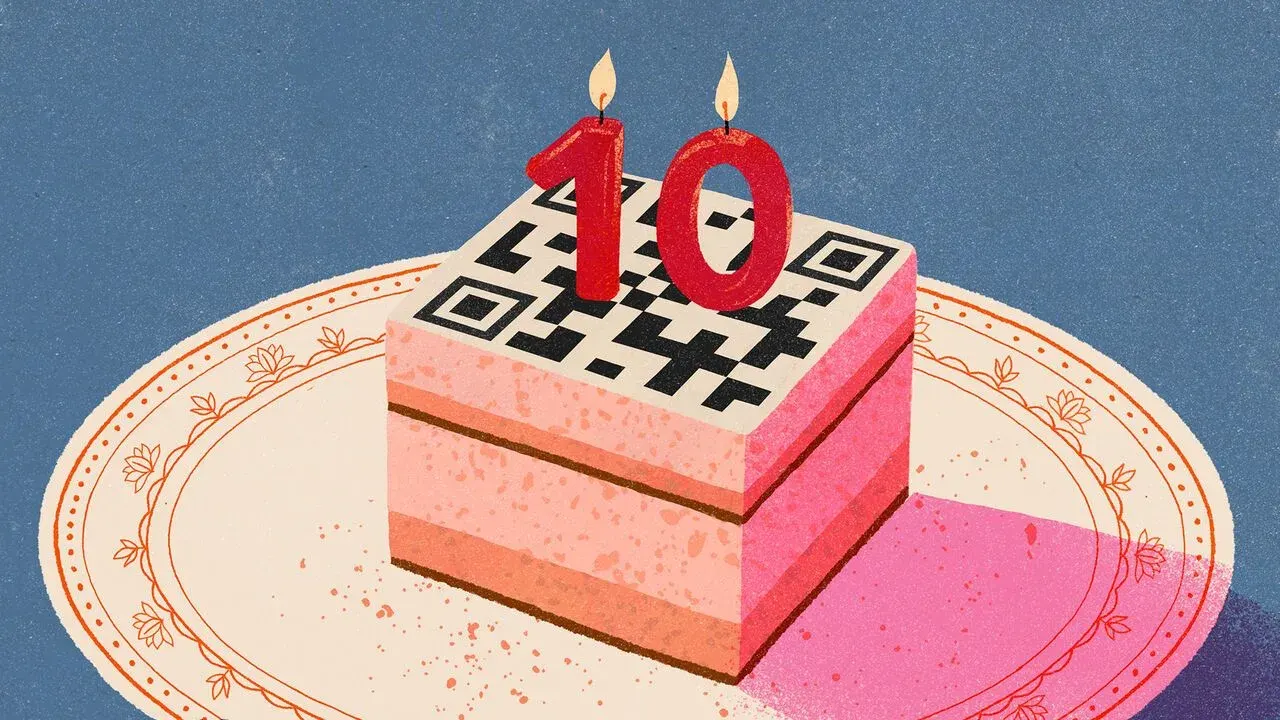
IT APPEARS on coconut piles above Mumbai beach carts, beside samosas in Delhi snack stalls and next to Navy Cuts at Kolkata tobacco kiosks. It decorates rickshaw seat-backs, power bills and Amazon’s payment screen. One scan settles a ten rupees- (ten cents-) packet of peanuts or a 100,000-rupee iPhone. Such routine has that QR symbol achieved — and such everyday status its scanning enjoys — that remembering its recent arrival on India’s streets takes effort.
Tens of billions of monthly transfers still cost nothing — and that is the problem
That QR pattern is the public face of Unified Payments Interface, or UPI, a network that marked its tenth anniversary on August 25th and which has transformed the movement of money across India.
From 73m to 25bn: how UPI scaled in ten years
In the stone age — prior to 2016 — cash covered nearly every transaction by count and two-thirds by value. Cheques made up most of the remaining non-cash activity. And for some reason no one ever admitted to holding small change, spawning a substitute currency of one-rupee boiled sweets.
During the 12 months following UPI’s debut, Indians completed 73m transactions valued at 227bn rupees through the system. In August of this year alone, usage hit 25bn transfers totalling nearly 30trn rupees. Over 85% of non-cash transactions now flow via UPI — cheques have shrunk to just 0.2%. Yet expansion can continue. The platform’s roughly 550m users represent only slightly more than half of India’s adults.
UPI transfers in August alone
Rupees moved that month
UPI users — just over half of adults
Why UPI took off: simplicity, cheap data and demonetisation
UPI’s triumph has multiple explanations. Foremost is straightforwardness. To send as well as collect funds, a user simply connects their bank account with a mobile app. Thereafter, paying requires merely scanning another person’s QR code or typing their phone number — no bank details to disclose, no plastic cards to manipulate and no point-of-sale terminal to approach.
Additional forces helped. Jio, a telecom operator, debuted in the same year as UPI. Its cut-throat tariffs sent mobile-data prices tumbling, pulling millions of Indians onto the internet — and therefore into UPI apps.
Narendra Modi’s shock move to demonetise 86% of cash by value in November that year — withdrawing 500- and 1,000-rupee notes, supposedly to penalise undeclared cash holdings — contributed as well. The measure damaged the informal economy and decelerated GDP growth, yet cashlessness predictably surged. UPI transactions climbed from 100,000 in October 2016 to 2m that December.
The zero-fee rule that made UPI ubiquitous
A further supportive, less harmful, measure was New Delhi’s move to prohibit charges on commercial UPI transactions. A shop taking a credit or debit card normally pays for that service. Such a charge gets divided among the network provider (such as Visa or Mastercard), the card-issuing bank and others. Since 2020, however, a merchant has incurred zero cost for taking payment through UPI. That also encourages take-up.
Parliament re-allows fees — but only for large merchants
Just ahead of UPI’s tenth anniversary, parliament enacted law re-allowing those fees. Although fresh rates remain unset, they are anticipated to cover solely commercial transactions and to sit above a floor that would spare most transfers, including those to the coconut seller, the rickshaw driver or between individuals. The concept is that large firms alone will pay.
Strangely for India, where big business draws little love, response has proved largely hostile. Opponents of the planned fees have contended that state expenditure is balanced by reduced currency-printing savings; that UPI’s advantages exceed its expenses; and that shoppers will eventually shoulder the load.
Why free payments still cost someone
At least that final claim seems to carry weight. Yet running UPI is not free. Oversight rests with the National Payments Corporation of India, a non-profit body jointly owned by public and private financial institutions. Banks lay out vast sums to sustain their networks, block fraud and keep payments clearing dependably. In exchange, official subsidies reimburse just a small share of their outlays.
Denied adequate financing, banks gain scant reason to fund innovation. More seriously, they can hardly maintain basic upkeep and anti-fraud defences. Consumers foot the bill already — but obliquely via taxes and through a service inferior to its potential.
Zero merchant fees accelerated adoption, but left banks to fund network upkeep and fraud protection from subsidies that cover only a small share of costs — a hidden charge paid through taxes and a weaker service.
What India got right — and what must come next
New Delhi merits credit for constructing UPI, for converting it into the spine of national payments and for choosing correctly on fees on two occasions. Yet none of that progress will matter greatly should the network atrophy or falter. For years UPI has let others settle bills. It must finance itself as well. ■
Subscribers to GlobeBriefly can sign up to our Opinion newsletter, which brings together the best of our leaders, columns, guest essays and reader correspondence.
KEEP THE CONVERSATION GOING
A good story is worth sharing.
Send this story to someone who values the bigger picture.
See more from GlobeBriefly on Google
Choose us as a preferred source in your Google preferences.